
Most people do not get into financial trouble because they cannot do math. They get into trouble because they are exhausted, stressed, and trying to solve an urgent problem with information that was designed to pull their eyes toward the promise, not the process.
The Headline Is Loud. The Cost Is Quiet.
That is why the fine print matters so much. The bold claim says relief, savings, lower payments, or faster results. The tiny text explains timing, conditions, fees, side effects, and what has to go right before any of the advertised benefits actually show up. If you have ever looked up a Freedom Debt Relief news review or compared debt solutions in general, this is the part worth slowing down for.
The real cost of almost any financial product is rarely the number in the headline. It is the chain reaction hidden underneath it. One fee leads to another. One delayed payment changes your credit profile. One “temporary” workaround turns into a long cleanup project. The damage often does not happen all at once. It happens quietly, through clauses most people skim when they are in a hurry.
Why Small Text Has So Much Power
Fine print works because it shows up after your emotions are already engaged. By the time you are reading the details, you may already be imagining the problem solved. That makes it easier to accept terms you would question in a calmer moment.
In personal finance, those terms can shape much more than price. They can affect when fees are earned, what happens if results take longer than expected, whether missed payments continue during the process, and how disputes get handled. According to the Federal Trade Commission, debt relief providers that market by phone must clearly disclose important information such as how long results may take, how much the service may cost, and possible negative consequences.
The FTC also states companies generally cannot charge fees before they have actually settled or resolved a debt. That should tell you something important. If regulators require those disclosures, it is because those details materially change the decision.
The Cheapest Looking Option Can Be the Most Expensive
A strange truth about money problems is that the option that feels easiest upfront can create the most friction later. A company may advertise a path that sounds simpler than calling creditors yourself, working with a nonprofit counselor, or changing your spending plan. But convenience has a price, and in debt situations that price is not always limited to a stated fee.
For example, the Consumer Financial Protection Bureau warns consumers to watch for debt settlement companies that promise to make debt go away, tell you to stop communicating with creditors, or tell you to stop making minimum payments. The bureau also notes that debt settlement companies are not allowed to collect fees before settling or resolving your debt.
That warning matters because the true cost may include more than service charges. It can include added interest, late fees, collection pressure, credit score damage, and the mental cost of uncertainty while you wait to see whether the plan works as hoped.
The Most Expensive Line Item Is Often Time
People usually look for the dollar amount in fine print. They should also look for the timeline.
Time is a hidden cost multiplier. If a process takes months or years, that affects your stress level, your ability to qualify for future credit, and your room to handle emergencies. A debt strategy that only works if you stay in a fragile holding pattern for a long period may cost more than it first appears, even if the advertised savings number looks impressive.
This is where careful reading beats wishful thinking. Ask practical questions. When are fees assessed? What conditions trigger them? What happens if one creditor does not cooperate? What are the likely effects on your account status while the process unfolds? What happens if you leave early?
Those are not cynical questions. They are the questions that reveal the product you are actually buying.
Marketing Sells Relief. Contracts Define Responsibility.
Another overlooked issue is responsibility transfer. Many ads are written to make it feel as though a company is taking the burden off your shoulders. Sometimes that is partly true. But contracts often show that the consumer still carries substantial risk.
You may still be responsible for staying current on certain obligations, reviewing documents, maintaining deposits, responding to notices, or accepting settlement terms. If a problem arises, the agreement may limit remedies, require arbitration, or narrow the company’s obligations in ways the ad never highlighted.
That gap between tone and contract language is where many expensive misunderstandings begin. The ad sells emotional certainty. The fine print restores legal uncertainty.
How to Read Fine Print Without Feeling Overwhelmed
You do not need a law degree to read carefully. You just need a system.
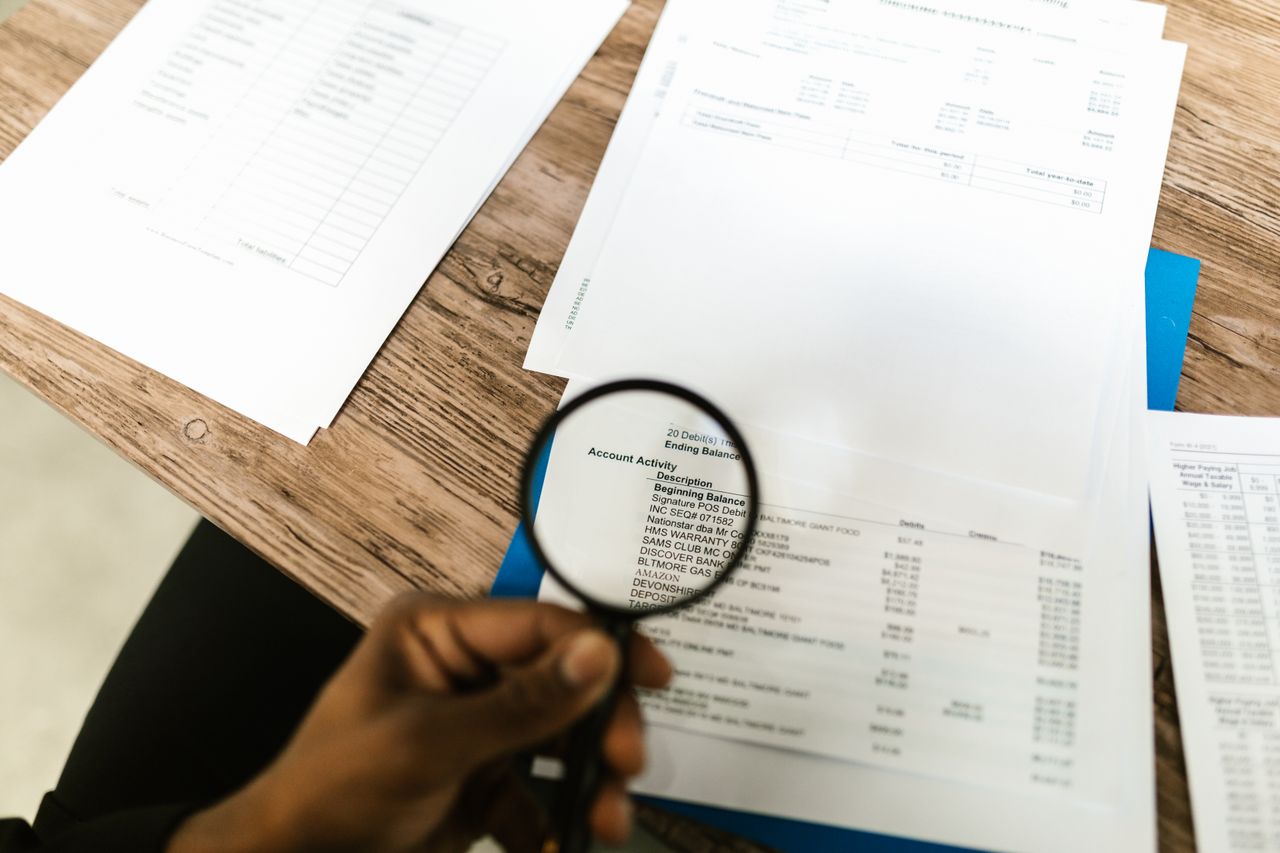
First, ignore the headline for a minute and scan for numbers. Find every fee, percentage, due date, and condition. Second, circle every word that weakens a promise, such as may, up to, estimated, typical, or subject to. Third, look for what has to happen before the best case outcome is even possible. Fourth, identify who bears the downside if things do not go as planned.
Most importantly, translate polished language into plain English. If a sentence is hard to understand, that is already useful information. Complexity is often part of the product.
The Fine Print Is Not the Side Story
People talk about fine print as if it were an annoying technical appendix. In reality, it is often the main event. The glossy message gets attention, but the quiet details determine whether a financial decision preserves your future or slowly drains it.
That is the deeper lesson here. Wealth is not only built by earning more or investing better. It is also protected by noticing where value leaks out. Hidden conditions, delayed consequences, and avoidable fees are all forms of financial erosion.
So the next time an offer sounds like instant relief, pause before reacting to the headline. The big letters are written to attract you. The small letters are written to bind you. If you want to know the real cost, look where the font gets tiny.
